Biotech's next growth cycle: Renewed confidence comes with conditions
There is a palpable shift in mood across biopharma. According to BIO-Europe's 2026 Biopharma C-Suite Agenda Survey, a clear majority of leaders expect partnering and dealmaking appetite to increase over the next 12 months, and 69% expect their own access to funding to improve. After several difficult years in which capital was harder to access and risk appetite contracted, this represents a genuine change in tone. Notably, raising growth capital and strategic partnering remain the most common planned activities, while relatively few respondents anticipate pursuing M&A specifically, a distinction worth holding onto as the sector's recovery takes shape.
Yet, a closer look at the same survey data reveals a more cautious picture underneath the optimism. Only 36% of respondents regard the current funding environment as primarily cyclical; 40% believe it reflects a mix of cyclical and structural pressures. Investor risk aversion, rather than interest rates, regulation, or asset quality, is identified overwhelmingly as the single biggest constraint on biotech investment. In other words, confidence is returning faster than conditions are genuinely easing, and the gap is most acute for early-stage companies that have yet to generate the kind of data that reassures increasingly selective investors.
This is the central tension facing the sector as it enters its next growth cycle: sentiment is recovering, but access to funding remains selective. The broad risk appetite that characterised earlier boom periods, when investors backed promise as much as proof, is unlikely to return in the same form. The next cycle will reward different behaviours.
A more discerning market
Renewed optimism does not remove the fundamentals of disciplined resource allocation, nor does it mean a return to funding development milestones for their own sake. Companies that mistake improving sentiment for a loosening of investor standards risk misallocating scarce resources at precisely the moment when discipline matters most.
What renewed confidence does mean is that funding is more likely to flow toward companies that can articulate with precision the questions that their next tranche of investment will enable them to answer, and how those answers will advance an asset's commercial or clinical trajectory. Leadership teams need to focus resources on the specific activities that most materially reduce risk and strengthen a company's position with investors or prospective partners, rather than spreading effort across a broader, but less differentiated, set of priorities. For European companies in particular, where the region scores a middling 2.8 out of 5 on competitiveness as a partnering and dealmaking hub, well behind the US and China, this discipline matters even more. Standing out in a crowded, selective global market requires clarity of purpose that generic optimism will not provide.
What this means for biotech companies
The bar for attracting investment and partners has risen. Scientific novelty remains the foundation of the industry, but is rarely sufficient on its own. Companies increasingly need a convincing data package, an efficient development plan, and a credible route towards partnering or commercialisation before they can expect serious engagement from investors or pharma partners.
This marks a shift in how progress itself is evaluated. Investors are less inclined to reward advancement to the next nominal development stage simply because it has occurred. What matters more is whether that progress generates evidence that resolves an important clinical, commercial, or development question. From the partnering side, conversations increasingly start with "What question does your next dataset answer?" rather than "What stage are you at?"
This is borne out directly in the survey data: when asked what pharma partners and investors now scrutinise most when assessing a company, the clinical data package ranked well ahead of operational track record, regulatory and CMC readiness, IP position, and strength of its leadership. The finding creates a real tension for biotech leaders: clinical data is what investors want most, but reaching the milestones needed to generate that data requires funding in the first place. Breaking that cycle requires resources to be directed deliberately toward the evidence that will meaningfully change an asset's risk profile or strategic value.
How companies should respond
The practical implication is that partnering strategy should be built alongside financial planning from the outset, not treated as a fallback once funding options narrow. Rather than being treated as simple financing events, partnerships should be positioned as routes to expertise, infrastructure, markets, and investment that a company could not easily build alone.
The survey reinforces this view: companies are preparing to fund their own programmes, generate data, and secure partnerships, with acquisitions remaining a secondary priority. This points to a market in which self-directed growth supported by targeted partnerships is the more realistic path for most companies.
Leadership teams should therefore be clear-eyed about where their own capabilities offer genuine advantage, and where outsourcing or partnering would add greater value. For early-stage companies in particular, partners can provide capabilities that would otherwise be costly and time-consuming to build in-house, such as CMC, regulatory expertise, and trial infrastructure. For many programmes, the most effective use of limited biotech resources may be to reach a compelling proof-of-concept milestone internally, then partner for the larger trials, manufacturing scale-up, or commercialisation that follow.
Timing matters as much as strategy. The best time to pursue a partner is rarely when cash reserves are running low. Financial planning and partnering strategy should be developed together well in advance, so that companies can negotiate from a position of choice, rather than necessity. Those that come to the partnering table early with runway still in hand consistently have more options and more leverage, than those arriving with a deal needed to survive.
A more mature growth cycle
The next biotech growth cycle may look markedly different from the last. Success will depend not on how much investment returns to the sector, but on how effectively companies convert it into meaningful evidence and durable partnerships.
Renewed confidence across biopharma is welcome and long overdue after a prolonged period of constraint. But confidence alone will not determine which companies thrive. The conditions attached to this recovery are clear: discipline in how resources are allocated, selectivity in where effort is focused, and a strategic, well-timed approach to partnership. These, not sentiment alone, will make the difference between failure and success.
About the author
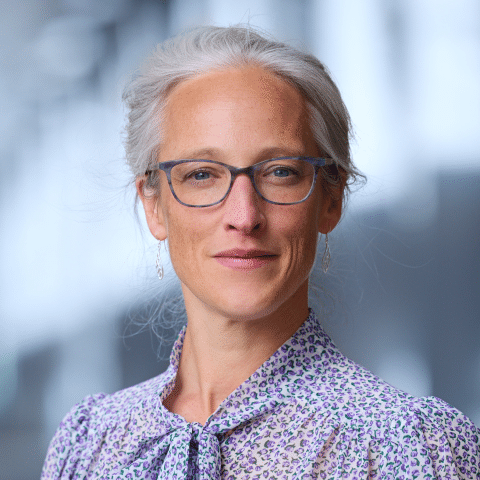
 Claire Macht is senior portfolio director, Europe, life sciences (partnering and investment), at Informa Connect. Macht brings nearly two decades of expertise in biotech partnering and strategic convening, having joined EBD Group (now part of Informa Connect) in 2007. Throughout her career, she has been instrumental in shaping the evolution of Europe's most significant biopharma partnering platforms, including BIO-Europe, BIO-Europe Spring, and Bio€quity Europe. Macht’s work focuses on how the biopharma industry is adapting to an increasingly complex global landscape. She is particularly passionate about Europe's unique position as a neutral, trusted convening ground for global decision-makers, especially as geopolitical uncertainty reshapes traditional collaboration models.